What is the market overview and industry significance of the Synthetic Graphite Material Market?
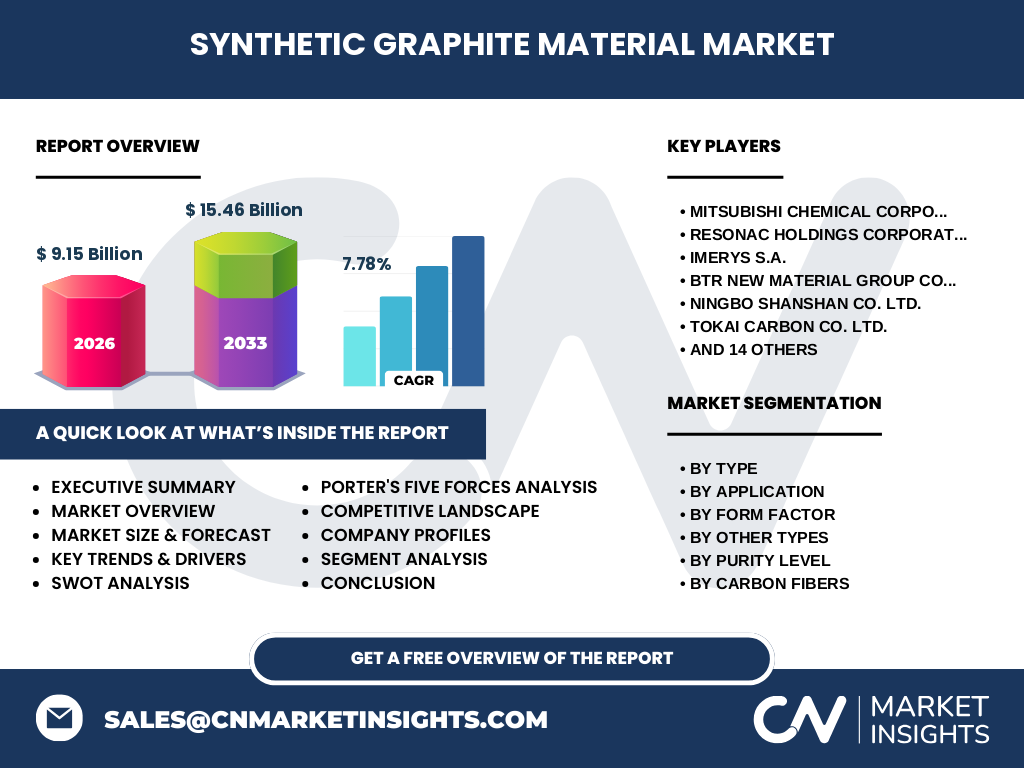
Our analysis indicates that the Synthetic Graphite Material Market represents a cornerstone for advanced manufacturing, valued at $9.15 Billion in 2026. This sector encompasses high-purity carbon materials engineered through graphitization at extreme temperatures exceeding 2500 degrees Celsius. These materials are critical for thermal management, electrical conductivity, and structural integrity across heavy industries like metallurgy and emerging lithium-ion battery supply chains globally.
Structural Growth Drivers, Restraints, Challenges, and Opportunities in the Synthetic Graphite Material Market
The market is propelled by exponential electric vehicle adoption and decarbonization mandates set by the International Energy Agency. However, stringent environmental regulations governing graphitization emissions and high energy consumption act as severe restraints. Conversely, surging demand for Ultra-High Power (UHP) graphite electrodes in electric arc furnaces and anode materials for lithium-ion batteries present immense commercial opportunities for market leaders.
Emerging Trends and Growth Patterns in the Synthetic Graphite Material Market
The shift toward silicon-carbon composite anodes is redefining the Synthetic Graphite Material Market. Industry innovators are integrating synthetic graphite powder and granular forms with silicon to enhance energy density in EV batteries. Furthermore, regional supply chain localization in North America and Europe is accelerating, reducing reliance on traditional Asian processing hubs and spurring domestic graphitization capacity investments.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic caused severe supply chain bottlenecks and temporary automotive manufacturing shutdowns, temporarily depressing demand for graphite electrodes and refractory applications. However, government-backed green stimulus packages post-pandemic accelerated the recovery trajectory. Demand rebounded sharply as Gigafactory investments surged, pushing the market toward a robust CAGR of 7.78% through the forecast period.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape of the Synthetic Graphite Material Market is moderately consolidated, dominated by vertically integrated giants such as Resonac Holdings Corporation, Mitsubishi Chemical Corporation, and Tokai Carbon Co. Ltd. These players maintain competitive advantages through proprietary graphitization technology and secure raw material access, while specialized innovators like Novonix Limited and BTR New Material Group Co. Ltd. capture high-growth battery sector shares.
Executive Summary of the Synthetic Graphite Material Market
Our comprehensive research demonstrates that the Synthetic Graphite Material Market is poised for exceptional expansion, escalating from $9.15 Billion in 2026 to reach $15.46 Billion by 2033 at a 7.78% CAGR. Growth is anchored by surging applications in lithium-ion batteries, electric arc furnace steelmaking, and specialized fuel cells. Stakeholders must navigate stringent carbon-neutrality mandates and high energy input costs to capitalize on these multi-billion-dollar opportunities.
Market Forecast and Long-Term Projections (2027-2033)
The data suggests that the Synthetic Graphite Material Market will achieve remarkable valuation milestones, expanding from its 2026 baseline of $9.15 Billion to $15.46 Billion by 2033. This 7.78% CAGR trajectory is driven by sustained volume requirements for synthetic graphite powder in energy storage systems and Ultra-High Power (UHP) graphite electrodes in green steel production.
Segmentation Analysis of the Synthetic Graphite Material Market
Market segmentation spans multiple categories tailored to industrial demands: By Type (Graphite Electrodes, Carbon Fibers, Specialty Graphite, Graphite Granular And Powder), By Application (Batteries, Refractories, Lubricants, Fuel Cells, Composites), By Form Factor (Powder, Granular, Bristle), By Other Types (Graphene, Artificial Graphite Blocks), By Purity Level (High Purity, Medium Purity, Low Purity), By Carbon Fibers (PAN, Pitch, Rayon-Based), By End User Industry (Automotive, Electronics, Aerospace, Energy, Consumer Goods), By Specialty Graphite (Expanded, Flexible, Foil), By Graphite Electrodes (UHP, HP, RP), and By Graphite Granular And Powder.
Regional Market Analysis and Geographic Performance
Asia-Pacific dominates the Synthetic Graphite Material Market industry trends, driven by massive manufacturing hubs in China, Japan, and South Korea, where companies like BTR New Material Group Co. Ltd. and Ningbo Shanshan Co. Ltd. operate. Meanwhile, North America and Europe represent high-growth regional markets fueled by domestic EV battery manufacturing incentives, stringent trade policies, and local processing investments by firms like Northern Graphite Corporation.
In-Depth Regional Review
In Asia-Pacific, integration with consumer electronics and EV supply chains underpins strong volume demand. Conversely, the North American and European markets prioritize supply chain security, prompting strategic investments in high-purity synthetic graphite production to bypass overseas trade restrictions. Regulatory frameworks like the U.S. Inflation Reduction Act heavily influence regional capital allocation toward localized graphitization facilities.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct strategic positioning: GrafTech International Ltd. and HEG Limited focus on high-performance graphite electrodes for steelmaking, whereas Mersen S.A. and SGL Carbon SE specialize in advanced specialty graphite and carbon fibers for aerospace and electronics. Meanwhile, Asian powerhouses like Fangda Carbon New Material Co. Ltd. and Jilin Carbon Co. Ltd. leverage scale economies to dominate high-volume commodity segments.
Porter's Five Forces Analysis of the Industry
Bargaining power of suppliers is moderate due to specialized petroleum coke and pitch raw materials. Threat of substitutes remains low given synthetic graphite's superior thermal and electrical properties in extreme environments. Industry rivalry is intense among established global titans, while the threat of new entrants is constrained by immense capital expenditure requirements and proprietary graphitization intellectual property.
SWOT Analysis of the Synthetic Graphite Material Market
Key strengths include exceptional thermal conductivity and high purity levels required by advanced technologies. Weaknesses involve high carbon emissions and energy intensity during graphitization. Opportunities lie in next-generation solid-state battery anodes and artificial graphite blocks. Threats encompass raw material price volatility and tightening environmental regulations enforced by bodies like the EPA and European Commission.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with petroleum refining by-products such as needle coke and coal tar pitch. Midstream processing involves shaping, baking, and graphitization at extreme temperatures—typically executed by players like Tokai Carbon Co. Ltd. and IMERYS S.A. Downstream distribution feeds directly into end-user manufacturing lines across automotive EV batteries, steel electric arc furnaces, and aerospace composites.
Investment Insights and High-Potential Areas
Our analysis indicates that high-potential investment areas center around green graphitization technologies utilizing renewable energy sources to mitigate carbon tax pressures. Investors should target high-purity synthetic graphite powder producers catering to the EV battery anode supply chain, as well as firms pioneering artificial graphite blocks for semiconductor manufacturing applications.
Conclusion and Key Takeaways
The Synthetic Graphite Material Market is on a definitive upward trajectory, scaling from $9.15 Billion in 2026 to $15.46 Billion by 2033. Driven by a 7.78% CAGR, success in this market requires navigating environmental hurdles while scaling production of high-purity grades for energy storage and electric arc steelmaking.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-level executives at firms like Toyo Tanso Co. Ltd. and Novonix Limited, and secondary macroeconomic indicators. We cross-reference production capacity data with end-user consumption metrics to ensure uncompromised market sizing accuracy.
Scope of the Report and Coverage Parameters
This report provides an exhaustive evaluation of the Synthetic Graphite Material Market analysis, covering historical data, the 2026 baseline of $9.15 Billion, and forecasts through 2033. Parameters encompass detailed segmentation across types, applications, form factors, and regions, though macroeconomic trade policy shifts outside our predictive window remain noted limitations.
Recent Developments in the Synthetic Graphite Material Market
Recent strategic moves feature major capacity expansions and joint ventures across the supply chain. For instance, companies like Novonix Limited have secured major commercial supply agreements with leading automotive OEMs, while traditional electrode manufacturers are retrofitting plants with energy-efficient graphitization furnaces to comply with tightening carbon reduction mandates across global industrial corridors.